- Hire in Japan
- Cost data
- Employer Cost in Japan 2026: A ¥6M Tokyo Salary, Line by Line
Employer Cost in Japan 2026: A ¥6M Tokyo Salary, Line by Line
In FY2026 a Tokyo employer pays ¥78,510 a month (15.70%) on top of a ¥6M salary for an office employee under 40. Each line is built from the official rate tables, with ¥4M and ¥10M shown so you can see where the caps start.
This article contains affiliate links. If you buy through them, we may earn a commission at no extra cost to you.
¥6,000,000 salary, Tokyo, office job, employee under 40, FY2026: the employer pays about ¥78,510 a month, or ¥942,120 a year. That is 15.70% on top of gross pay.
At ¥4M the figure is 15.99%. At ¥10M it falls to 13.59%, because the pension cap holds the largest line flat.
If the employee is 40 to 64, add 0.81%.
Checked in Tokyo on 2026-10-15. The figures come from the Japanese originals: Kyokai Kenpo's FY2026 Tokyo premium table, 日本年金機構's pension and bonus pages, 厚生労働省's FY2026 employment insurance and workers' accident rate notices, and こども家庭庁's page on the new child support levy.
This is general information, not advice for your specific case. For a real hire, have a licensed 社会保険労務士 (sharoushi, labour and social insurance consultant) or a lawyer check your payroll setup.
In this article
- What you pay on top of salary in Tokyo, FY2026
- How these numbers were built
- The line-by-line table at ¥4M, ¥6M and ¥10M
- What the table means for your budget
- Why vendor blogs quote 11.9% to 18%
- What changed in 2026
- The Japanese rules behind the caps
- Where budgets usually go wrong
- How to check an EOR quote against these numbers
- Recap
What you pay on top of salary in Tokyo, FY2026
This section gives you the one number to put in the budget, and shows where it comes from.
The employer pays seven statutory lines. Four are 社会保険 (shakai hoken, social insurance): health, pension, and two child-related levies. Three are 労働保険 (roudou hoken, labour insurance): employment insurance, workers' accident insurance, and a very small asbestos levy. Before any EOR fee, the uncapped employer rate for an office employee under 40 in Tokyo is 15.702%.
The pension line is more than half the total. The two child levies are under ¥2,400 a month together. They are also the lines most often missing from vendor examples, so check for them first on any quote.
How these numbers were built
Read this before you change the assumptions. With these steps you can rebuild every figure in the article.
Assumptions: salary paid in 12 equal monthly amounts, no bonus, no commuting allowance, employee under 40, company insured with 協会けんぽ (Kyokai Kenpo) Tokyo branch, business class 94 "その他の各種事業" (other businesses) for workers' accident insurance, and 一般の事業 (general business) for employment insurance.
Two different bases. This trips up most spreadsheets:
- Social insurance lines (health, pension, both child levies) are charged on the 標準報酬月額 (hyoujun houshuu getsugaku, standard monthly remuneration). This is a fixed grade from the official table, not the exact salary.
- Labour insurance lines (employment, workers' accident, asbestos) are charged on actual wages paid. The 大阪労働局 formula is 賃金総額 × (workers' accident rate + employment insurance rate). Wages for this purpose include bonuses and commuting allowance, including the tax-free part. They exclude retirement pay and expenses for business travel (福井労働局 table).
Rates used, all FY2026:
| Line | Japanese term | Total rate | Employer share | Base | Source |
|---|---|---|---|---|---|
| Health insurance, Tokyo | 健康保険 | 9.85% | 4.925% | standard grade | Kyokai Kenpo FY2026 |
| Long-term care (ages 40–64 only) | 介護保険 | 1.62% | 0.81% | standard grade | same |
| Child support levy (new) | 子ども・子育て支援金 | 0.23% | 0.115% | standard grade (health) | こども家庭庁 |
| Employees' pension | 厚生年金 | 18.3% | 9.15% | standard grade, capped at ¥650,000 | 日本年金機構 |
| Child-rearing contribution | 子ども・子育て拠出金 | 0.36% | 0.36% (employer only) | pension grade | same |
| Employment insurance | 雇用保険 | 1.35% | 0.85% | actual wages | 厚生労働省 FY2026 |
| Workers' accident, class 94 | 労災保険 | 0.3% | 0.3% (employer only) | actual wages | 厚生労働省 rate table |
| Asbestos relief levy | 一般拠出金 | 0.002% | 0.002% (employer only) | actual wages | 栃木労働局 |
← Scroll sideways to see more →
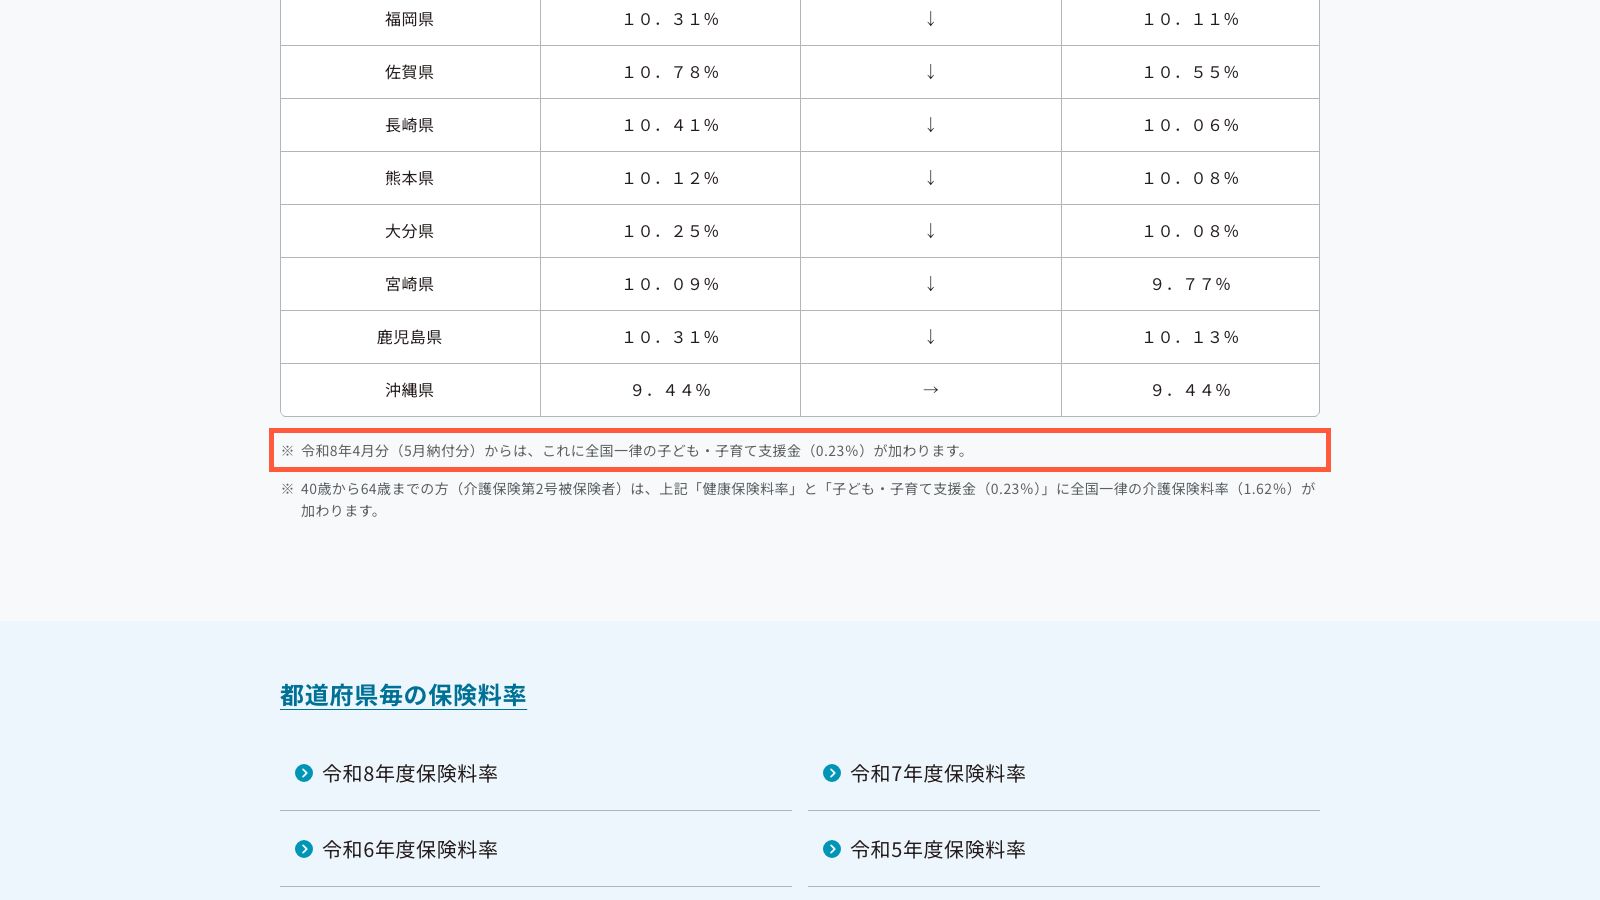
Each rate covers a specific period. The Tokyo health rate applies from the March 2026 premium, which is paid in April. The child support levy starts with the April 2026 premium, deducted from May pay. The employment insurance rate runs from 1 April 2026 to 31 March 2027. The pension rate has been 18.3% since September 2017.
The line-by-line table at ¥4M, ¥6M and ¥10M
Here are the yen figures you can hold up against a payslip or an EOR invoice.
Standard grades used, from the Tokyo table: ¥340,000 for ¥4M (¥333,333 a month), ¥500,000 for ¥6M, and ¥830,000 for health with ¥650,000 for pension at ¥10M (¥833,333 a month).
| Item | Legal basis | FY2026 rate (employer) | Who pays | ¥/month at ¥4M | ¥/month at ¥6M | ¥/month at ¥10M |
|---|---|---|---|---|---|---|
| Health insurance (Tokyo) | 健康保険法 | 4.925% | split 50/50 | 16,745 | 24,625 | 40,877.5 |
| Child support levy | 子ども・子育て支援法 | 0.115% | split 50/50 | 391 | 575 | 954.5 |
| Employees' pension | 厚生年金保険法 | 9.15% | split 50/50 | 31,110 | 45,750 | 59,475 (capped) |
| Child-rearing contribution | 子ども・子育て支援法 | 0.36% | employer only | 1,224 | 1,800 | 2,340 (capped) |
| Employment insurance | 雇用保険法 | 0.85% | employer 8.5 / employee 5 per 1,000 | 2,833 | 4,250 | 7,083 |
| Workers' accident (class 94) | 労災保険法 | 0.3% | employer only | 1,000 | 1,500 | 2,500 |
| Asbestos levy | 石綿健康被害救済法 | 0.002% | employer only | 7 | 10 | 17 |
| Total per month (¥) | 53,310 | 78,510 | 113,247 | |||
| Total per year (¥) | 639,720 | 942,120 | 1,358,964 | |||
| Share of gross salary | 15.99% | 15.70% | 13.59% |
← Scroll sideways to see more →
The ¥4M and ¥10M figures are rounded to the nearest yen. The official table shows employer halves to ¥0.5. Under payroll rounding rules the employee's deduction is rounded, so the employer's actual payment can differ by about ¥1 a month on each line.
The employee pays too, through payroll deduction: 4.925% health, 0.115% child support levy, 9.15% pension and 0.5% employment insurance. None of that is your cost. It does mean the employee's take-home pay is lower than gross, which is worth explaining in the offer letter.
What the table means for your budget
Find your case in the list and use that number.
- If you are hiring at ¥4M–¥7.6M, under 40, in an office: budget 15.7%, plus a few tenths of a percent for grade rounding. The ¥4M case comes out at 15.99% because ¥333,333 falls in the ¥340,000 grade, so you pay on ¥6,667 more than the actual salary.
- If the employee is 40 to 64: add the employer half of long-term care, 0.81%. At ¥6M that is ¥4,050 a month, which brings the total to ¥82,560 a month, ¥990,720 a year, or 16.51%.
- If you are hiring above about ¥7.62M: the pension cap applies, and each extra yen of salary carries only about 6.2% employer cost (health, child support levy and labour lines: 4.925 + 0.115 + 0.85 + 0.3 + 0.002 = 6.192%) instead of 15.7%. At ¥10M the overall share is 13.59%.
- If the role is IT, publishing or finance: workers' accident class 97 (通信業、放送業、新聞業又は出版業) and class 99 (金融業、保険業又は不動産業) are 2.5/1,000, not 3/1,000. At ¥6M that saves ¥250 a month. Whoever is the legal employer, often the EOR, chooses the class.
The pension cap is the part I would underline for a CFO. Between ¥4M and ¥7.6M the percentage barely moves. After that it falls steadily. A flat 16% assumption overstates a ¥10M hire by about ¥240,000 a year.
Why vendor blogs quote 11.9% to 18%
Each vendor figure is a correct answer under a different set of assumptions. This section matches them up.
| Vendor page (date shown on page) | Figure quoted | What it assumes |
|---|---|---|
| Teamed, Japan cost breakdown (last reviewed 13 June 2026) | "approximately 14% to 16%"; worked example ¥76,125 at ¥500,000/month | Tokyo, under 40, four lines: pension, health, employment, workers' accident |
| Deel, employer costs in Japan (updated 9 June 2026) | ¥1,862,365 on ¥15,695,000, about 11.9% | High salary, so the pension cap applies; includes long-term care, childcare contribution and asbestos levy |
| Playroll, Japan employment cost | "roughly 14%-18%" | Range across roles, subject to statutory caps |
← Scroll sideways to see more →
Teamed's example matches the official Tokyo table to the yen on the four lines it shows: ¥45,750 pension, ¥24,625 health, ¥4,250 employment, ¥1,500 workers' accident. Add the two child levies (¥575 + ¥1,800 = ¥2,375) and you get ¥76,125 + ¥2,375 = ¥78,500. Adding the ¥10 asbestos levy gives the ¥78,510 in this article. Deel's low percentage follows from salary level. At ¥15.7M the pension is capped at ¥59,475 a month (its ¥713,700 a year is exactly 12 times that), so the share falls.
For a mid-level Tokyo hire under 40, the official tables come out at 15.7%, near the middle of the published ranges. You will not find 40% from statutory insurance alone. Totals that high include fees, benefits or bonuses as well.
What changed in 2026
Three lines moved this fiscal year. Two went down and one is new.
| Change | FY2025 | FY2026 | Effect at ¥6M, per month |
|---|---|---|---|
| Tokyo health rate (total) | 9.91% | 9.85% | employer saves ¥150 |
| Employment insurance, employer share | 9/1,000 | 8.5/1,000 | employer saves ¥250 |
| Child support levy (new) | — | 0.23% (employer 0.115%) | employer adds ¥575 |
| Child-rearing contribution | 0.36% | 0.36% | no change |
| Workers' accident rates | — | same as FY2025 | no change |
← Scroll sideways to see more →
The changes nearly cancel out: about ¥175 more a month at ¥6M. The more useful point is that the new levy appears as its own line on payslips and on Kyokai Kenpo's premium table.
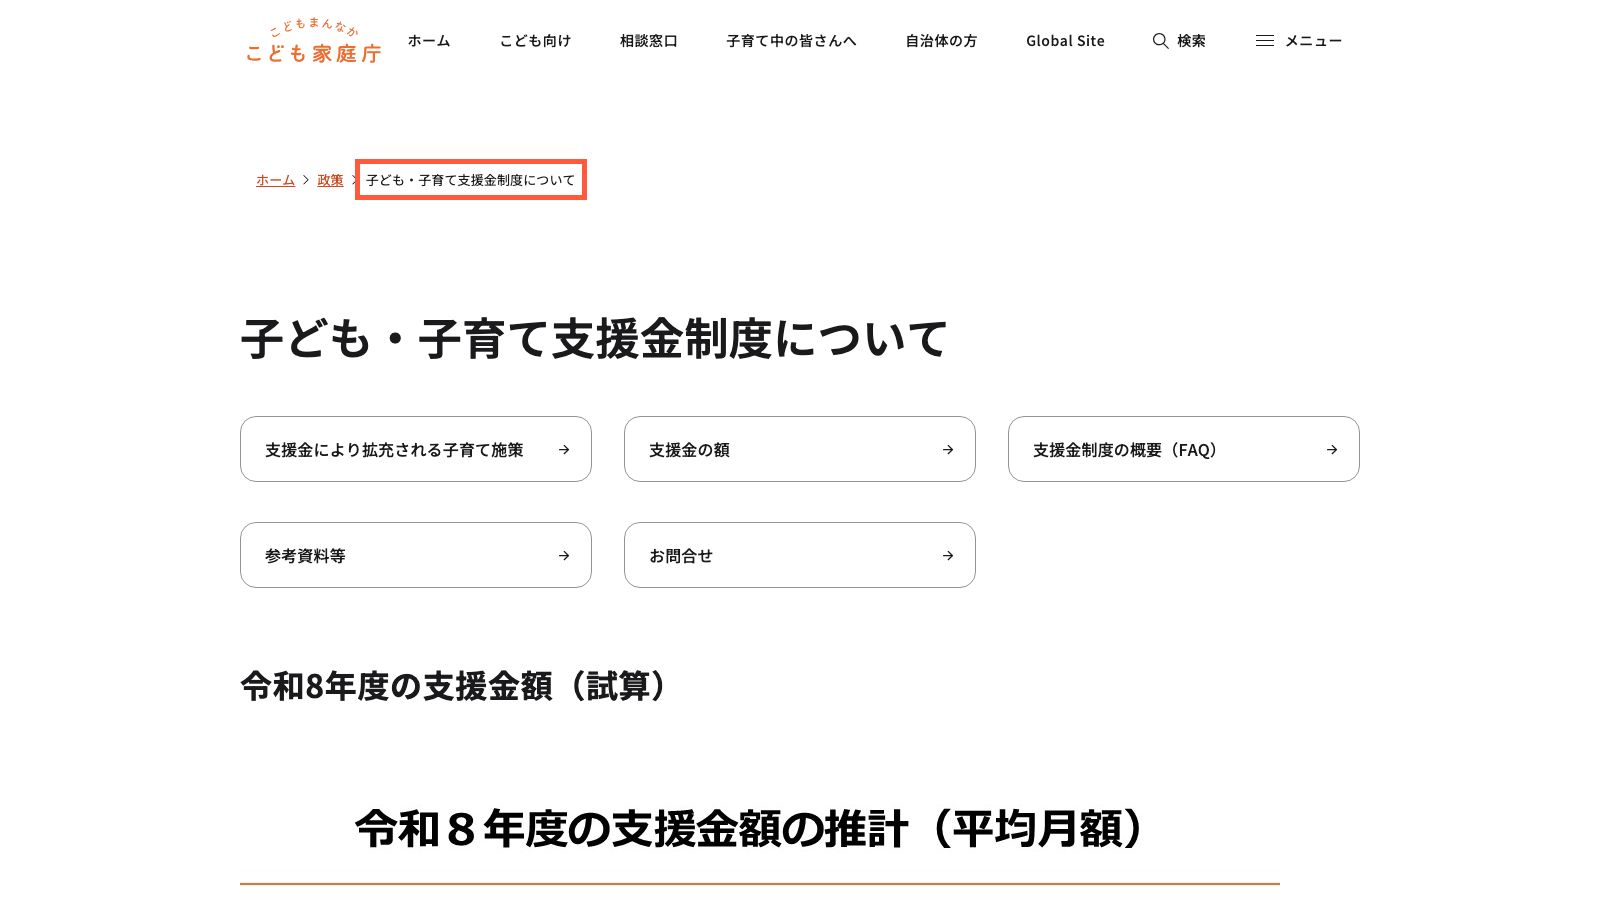
The two child levies are separate charges, and this causes confusion. The 支援金 (shienkin, support levy) is new, 0.23%, split 50/50, and charged on the health-insurance grade. こども家庭庁 says half of the levy is basically borne by the company. The 拠出金 (kyoshutsukin, contribution) has existed for years, is 0.36%, is paid by the employer only, and is charged on the pension grade, so the ¥650,000 cap applies to it. 日本年金機構 confirms the FY2026 rate is unchanged at 0.36%.
日本年金機構’s premium table page, including the standard remuneration capを見る(nenkin.go.jp)
The Japanese rules behind the caps
These are the rules that come from Japanese law and that most English guides leave out. They are what move the cost for senior hires.
Two caps at two levels. The pension grade tops out at ¥650,000 (grade 32), which applies once monthly pay reaches ¥635,000, about ¥7.62M a year paid in 12 equal amounts. Health insurance tops out much higher, at grade 50, ¥1,390,000, which applies from ¥1,355,000 a month, about ¥16.26M a year. Between those two points, pension is fixed and health keeps rising.
Bonuses have separate caps. Under 日本年金機構's bonus rules, pension and the 拠出金 are capped at ¥1.5M per month (1カ月あたり150万円). Bonuses paid in the same month are added together before the cap applies. Health insurance, long-term care and the support levy are capped at ¥5.73M in total per fiscal year (April–March). Labour insurance has no cap and applies to every yen.
Three payments a year or fewer count as bonuses. Pay made four or more times a year is added into the standard monthly grade instead. This decides which cap applies.
Here is the effect. Take ¥10M paid as ¥650,000 × 12 plus two ¥1.1M bonuses. Each monthly payment already sits at the pension cap, but each bonus is charged pension in full because it is under ¥1.5M. By my calculation the employer cost is about ¥1,570,200 a year (15.70%), against ¥1,358,964 for 12 equal payments. That is about ¥211,000 more for the same total pay.
Japanese offer letters often split pay this way because summer and winter bonuses are customary. If the candidate expects bonuses, model them in your budget, not just the annual figure.
The cap moves in September 2027. Under the law passed on 13 June 2025, the pension cap rises to ¥680,000 in September 2027, ¥710,000 in September 2028 and ¥750,000 in September 2029 (厚生労働省). The ¥10M row above is correct for FY2026 only. Expect it to rise each September from 2027.
Where budgets usually go wrong
These are the mistakes that change the cost, roughly in order of size.
- Bonuses not modelled. The ¥211,000 example above. This matters most for senior hires.
- Missing the 40th birthday. Long-term care premiums apply to employees aged 40 to 64 (Kyokai Kenpo's FY2026 rate table) and add 0.81% for the employer. A 39-year-old hire becomes more expensive within a year.
- Leaving out commuting allowance. It is normal in Japan, it counts toward the standard grade, and it counts as wages for labour insurance. It can move the employee up a grade.
- Missing the two child levies. Together they add 0.475% at mid salaries.
- Treating a 健康保険組合 (kenpo kumiai, company health society) rate as an error. Many EORs and larger employers are insured through their own health society instead of Kyokai Kenpo, at a different rate. That is a legitimate reason a quote differs from this article's numbers.
- Forgetting the annual true-up. Labour insurance is prepaid and then settled in the 年度更新 (nendo koushin, annual renewal), which runs from 1 June to 10 July in 2026. If bonuses were higher than estimated, you get a top-up bill.
None of this covers paid leave, customary bonuses, 退職金 (retirement allowance, not legally required), recruitment, equipment or the EOR's own fee. All of those are extra.
How to check an EOR quote against these numbers
The aim here is to separate the EOR's fee from the statutory cost on the quote.
Take the monthly yen figure for your salary from the table, or rebuild it with the rates above if your salary is different. Put it next to the line on the quote labelled "employer contributions" or "statutory costs". A difference of a few tenths of a percent is explained by grade rounding, commuting allowance, the employee's age or the workers' accident class. Anything well beyond that is fee or buffer, and you are entitled to ask which.
Four questions to send the vendor:
- Which health insurer are you enrolled in, Kyokai Kenpo Tokyo or a 健保組合, and at what FY2026 rate?
- Does your line include the 子ども・子育て支援金 (0.115%) and the 子ども・子育て拠出金 (0.36%)?
- Which workers' accident business class will you register this role under?
- How do you bill the annual labour insurance true-up, and how do you handle bonus months?
Recap
- FY2026, Tokyo, office, under 40: ¥78,510 a month at ¥6M, 15.70% of gross.
- At ¥4M expect about 16%. Above about ¥7.62M the pension cap brings the share down, to 13.59% at ¥10M.
- Add 0.81% from age 40. Use 2.5/1,000 workers' accident for IT, publishing or finance roles.
- Two bonuses can add about ¥211,000 a year to a ¥10M package compared with 12 equal payments.
- The pension cap rises in September 2027, and health and support levy rates are reset every fiscal year (Kyokai Kenpo health rates apply from the March premium, paid in April), so recheck then.
Next action: put your salary into the table above, write down the monthly yen figure, and set it next to the statutory-cost line on each EOR quote before you compare their fees. Rates in this article were checked on 2026-10-15.
Sources
- 令和8年度保険料率 (全国健康保険協会(協会けんぽ)), accessed 2026-10-15
- 令和8年3月分からの健康保険・厚生年金保険の保険料額表(東京支部) (全国健康保険協会(協会けんぽ)), accessed 2026-10-15
- 子ども・子育て支援金制度について (こども家庭庁), accessed 2026-10-15
- 保険料額表(令和2年9月分~) (日本年金機構), accessed 2026-10-15
- 賞与を支払ったときの手続き (日本年金機構), accessed 2026-10-15
- 令和8(2026)年度 雇用保険料率のご案内 (厚生労働省), accessed 2026-10-15
- 令和8年度の雇用保険料率について (山形労働局), accessed 2026-10-15
- 令和8年度の労災保険率等について (厚生労働省), accessed 2026-10-15
- 令和8年度 労働保険の年度更新について (栃木労働局), accessed 2026-10-15
- 労働保険料の計算方法 (大阪労働局), accessed 2026-10-15
- 賃金総額算入早見表 (福井労働局), accessed 2026-10-15
- 厚生年金等の標準報酬月額の上限の段階的引上げについて (厚生労働省), accessed 2026-10-15
- Japan cost breakdown (Teamed), accessed 2026-10-15
- Employer costs for an employee in Japan (Deel), accessed 2026-10-15
- Japan employment cost (Playroll), accessed 2026-10-15